Where CHOCs fits
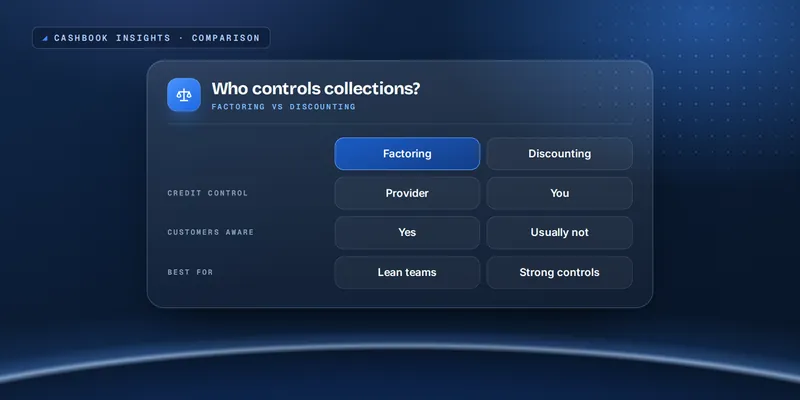
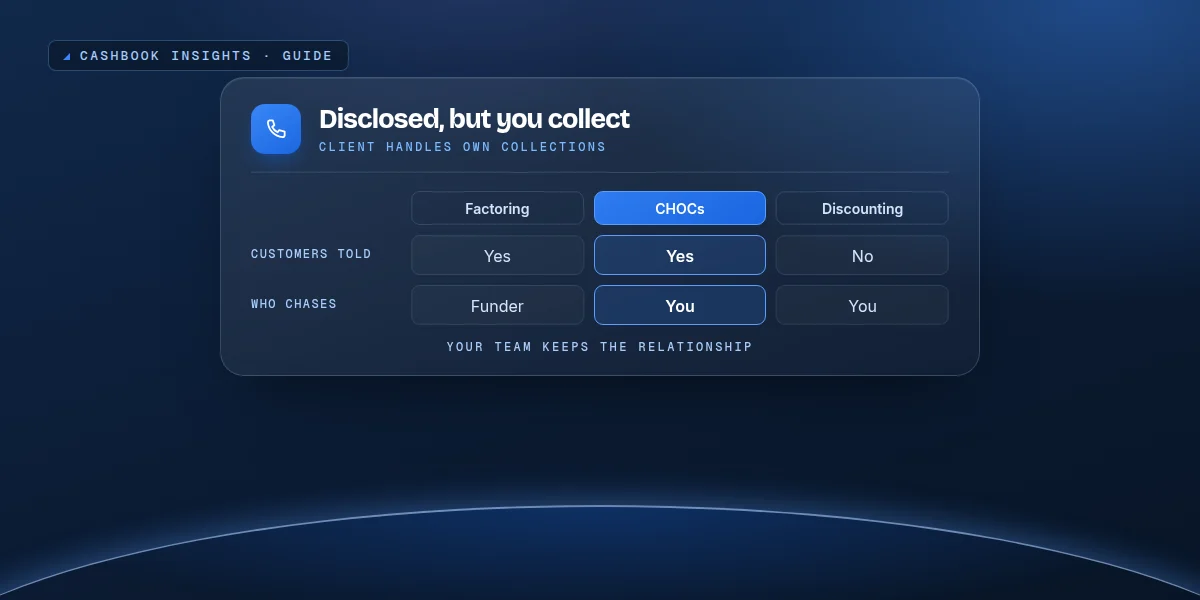
| Factoring | CHOCs | Confidential invoice discounting | |
|---|---|---|---|
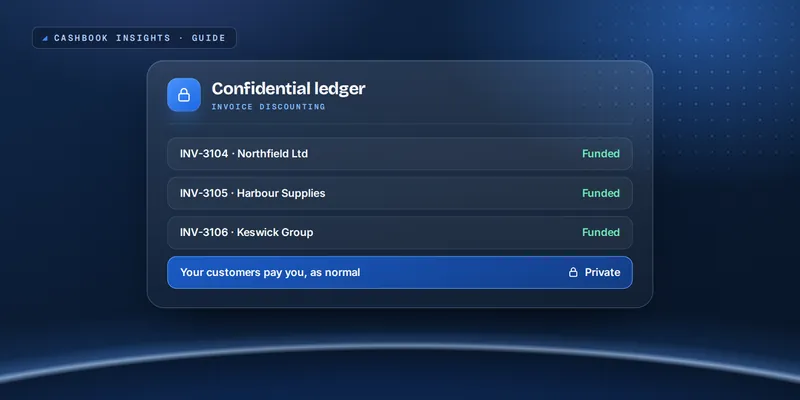
| Customers told a funder is involved | Yes | Yes | No |
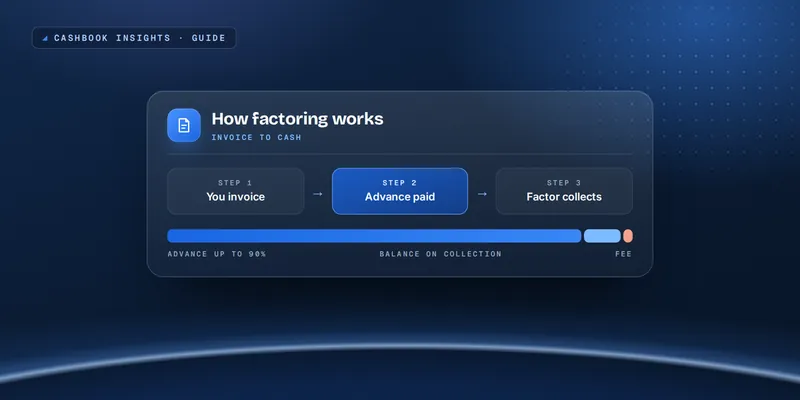
| Who chases payment | The funder | Your business | Your business |
| Typical business | Smaller or growing firms wanting collections support | Firms with capable credit control that do not need confidentiality | Established firms with strong systems and reporting |
Why a business might choose it
- You keep the customer relationship. Your team does the chasing, in your own style.
- It can be available earlier than confidential discounting. Because payments go to a funder-controlled account, the funder has more visibility, which can make it an option for businesses that are not yet ready for confidential terms.
- Often lower cost than full factoring, as the funder is not running your collections.
What to weigh up
- Customers will know a funder is involved (usually through a notice on invoices).
- Your credit control has to be consistent: availability falls if collections slip.
- Reporting and reconciliation are still required.
Compare the main options in factoring vs invoice discounting, or see the invoice factoring and invoice discounting pages.
CHOCs: a practical decision test
CHOCs fits when you want your own team to stay in charge of collections but do not need the arrangement to be confidential.
Commercial fit
Suits businesses with capable credit control that are not yet ready, or do not want to pay, for confidential invoice discounting.
Evidence and eligibility
Funders look for consistent collections, clean ledger reporting and customers who pay into the controlled account.
Operational fit
Your team still chases every invoice. Availability falls if collections slip, so staffing and discipline matter.
Alternatives
Full factoring if you want collections handled for you; confidential invoice discounting once systems and track record support it.
CHOCs: model the downside, not just the headline
Model what happens to availability if debtor days lengthen by two or three weeks, and whether your team can carry the collections workload in a busy month.
Where this can go wrong
Customers will see the funder’s notice on invoices. If a key customer would react badly to disclosure, discuss it before choosing a disclosed structure.
CHOCs: questions to ask before signing
- How will customers be notified, and what will invoices say?
- What reporting is required, and how often?
- How is availability calculated as debtor days change?
- What would it take to move to confidential terms later?
CHOCs: documents and controls to prepare
Every invoice finance discussion goes better with the same core pack: a current aged-debt report, representative contracts and invoices with delivery or acceptance evidence, recent management accounts with a short cash forecast, and an honest schedule of credit notes, bad debts and customer concentration. We keep one maintained resource covering the full pack, the questions that surface the all-in cost, and what to monitor once a facility is live - read the invoice finance preparation checklist.
This guide is general information, not a recommendation or an offer of finance.