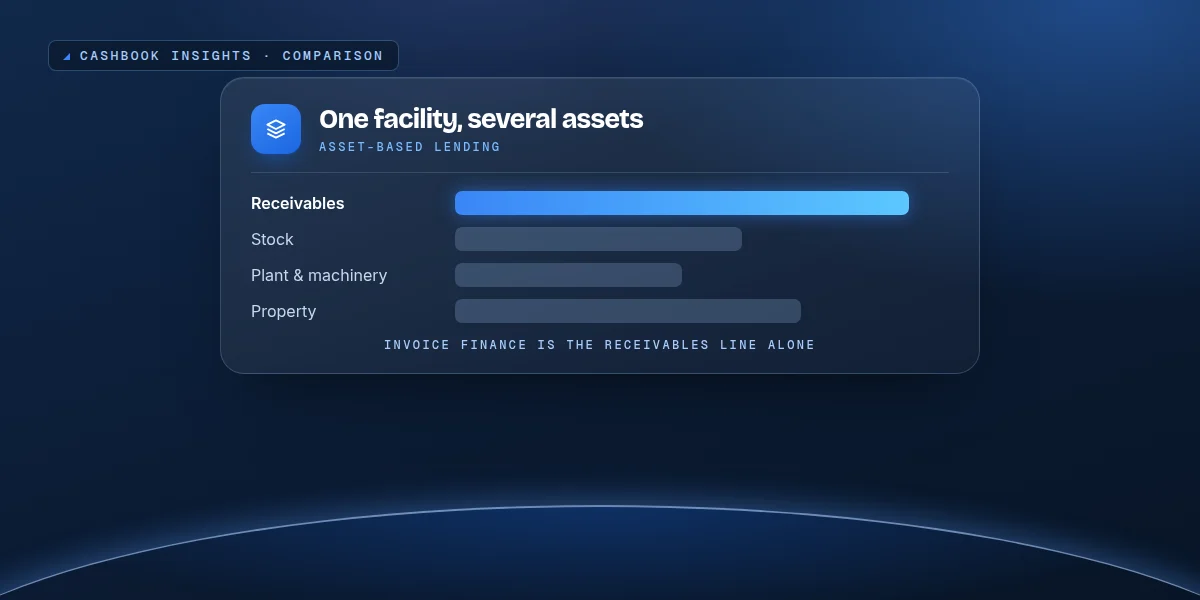
What an ABL facility can include
| Asset | Typical role in ABL |
|---|---|
| Receivables (invoices) | The core: funded like invoice finance |
| Stock / inventory | Funded at a lower percentage, based on what it would realise |
| Plant and machinery | Term loan against valued equipment |
| Property | Term loan against commercial property |
| Cash flow | Sometimes a cash-flow loan on top |
When invoice finance alone is enough
- Most of your working capital is tied up in unpaid invoices;
- You have little stock, or it moves quickly;
- You want a facility that grows with sales without complex asset valuations.
When ABL may be worth exploring
- Large amounts of stock or equipment that could support more borrowing;
- A refinancing, acquisition or turnaround where you need to borrow against everything the business owns;
- Turnover and asset values large enough to justify the monitoring and valuation costs.
Building the equivalent from separate facilities
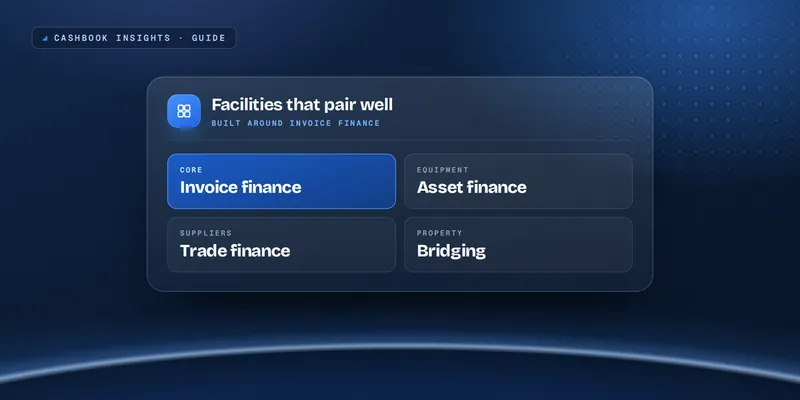
Some businesses combine invoice finance with other specialist facilities rather than one ABL: for example invoice finance for receivables, trade finance for stock purchases, and asset finance for equipment. See funding options that pair with invoice finance.
Asset-based lending: a practical decision test
Asset-based lending is worth the complexity when stock, equipment or property could support meaningful extra borrowing. If your working capital is mostly unpaid invoices, invoice finance is simpler.
Commercial fit
Suits larger businesses with significant assets, often for refinancing, acquisitions or growth that needs more than receivables can support.
Evidence and eligibility
Expect valuations of stock and equipment, regular stock reports and field audits, as well as ledger reporting.
Operational fit
Monitoring is heavier than invoice finance alone; finance teams report on several asset classes.
Alternatives
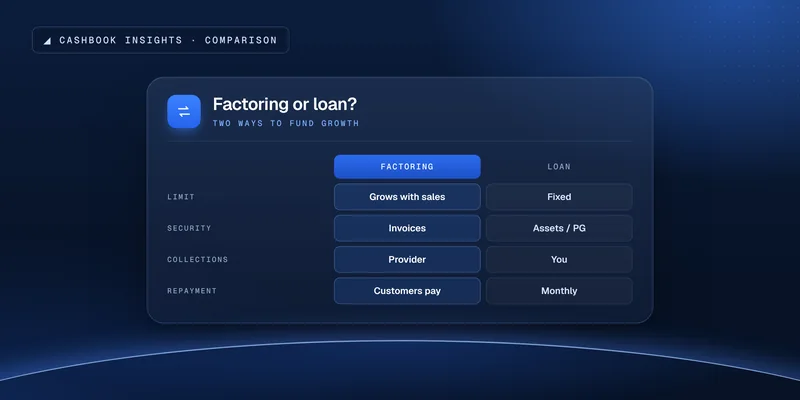
Combine invoice finance with trade finance for stock and asset finance for equipment as separate, simpler facilities.
Asset-based lending: model the downside, not just the headline
Model availability if stock values are marked down or equipment is revalued, since those advance rates move more than receivables.
Where this can go wrong
More security does not always mean more usable funding. Low advance rates on stock and the cost of valuations and monitoring can make the extra headroom smaller than expected.
Asset-based lending: questions to ask before signing
- What advance rate would apply to each asset class?
- How often are stock and equipment revalued?
- What reporting and audits are required?
- How does the cost compare with separate facilities?
Asset-based lending: documents and controls to prepare
Every invoice finance discussion goes better with the same core pack: a current aged-debt report, representative contracts and invoices with delivery or acceptance evidence, recent management accounts with a short cash forecast, and an honest schedule of credit notes, bad debts and customer concentration. We keep one maintained resource covering the full pack, the questions that surface the all-in cost, and what to monitor once a facility is live - read the invoice finance preparation checklist.
This guide is general information, not a recommendation or an offer of finance.