

Short-term property funding where the main issue is timing and a clear exit.
Funding comparison · decision guideFCA-registered UK lender FRN 782472 (opens the FCA register in a new tab)
Bridging vs development finance.
A bridge funds a short timing gap with a defined exit. Development finance funds build work, staged drawdowns and project risk. Treating one as the other creates delays, wrong pricing and weak lender fit.
Read aloud by your browser
Bridging structure check
A £325,000 loan against a £500,000 property
65%
loan-to-value, against a 70% illustrative reference point
- Equity remaining
- £175,000
- Headroom to 70% LTV
- £25,000
Within a 70% illustrative LTV reference point.
A £325,000 loan against a £500,000 property is 65% loan-to-value; equity remaining £175,000.
Security risk: Your property may be repossessed if you do not keep up repayments on a loan secured against it.
Project funding for build, conversion or refurbishment costs across staged work.
Use bridging when the asset already supports the loan. Use development finance when value depends on works being completed.
Decision guide
Bridging or development finance: the practical difference.
The right comparison is not simply the lowest headline rate. Match the facility to the asset being funded, the evidence available, the expected duration, the operational work required and the event that repays it. A cheaper product used for the wrong job can create more delay, covenant pressure or refinancing risk than a correctly structured specialist facility.
Bridging suits purchases, refinance gaps, auction deadlines and light works.
A bridge needs a clear sale, refinance or other exit.
Poor cost control, planning or build risk can derail development funding.
| Question | Usually stronger when | Watch-out |
|---|---|---|
| Purpose | Bridging suits purchases, refinance gaps, auction deadlines and light works. | Development finance suits heavier construction or staged build costs. |
| Repayment | A bridge needs a clear sale, refinance or other exit. | Development finance depends on build progress, monitoring and exit value. |
| Speed | Bridging can move quickly when title, value and exit are clear. | Development facilities take more technical review. |
| Main risk | Weak exit or tight LTV kills a bridge. | Poor cost control, planning or build risk can derail development funding. |
Worked example
A light refurbishment on a bridge.
An investor buys a £450,000 house needing cosmetic works with a £300,000 bridge and sells in month 10.
Cosmetic works fit a bridge; structural or new-build work moves the project towards development finance.
| Property value | £450,000 |
|---|---|
| Gross loan (66.7% loan-to-value) | £300,000 |
| Arrangement fee, 1%, from the loan | £3,000 |
| Interest at 1% a month, rolled up, for 10 months | £30,000 |
| Repaid at exit (loan plus interest) | £330,000 |
| Cost before valuation and legal fees | £33,000 |
| If the exit is 3 months late | +£9,000 in interest |
Illustrative: interest at 1% a month, rolled up, and an arrangement fee of 1% of the loan. Valuation and legal costs are extra and quoted per case. Bridging finance is secured against property, which may be repossessed if repayments are not maintained.
Decision framework
Bridging or development finance: use the comparison to make a funding decision.
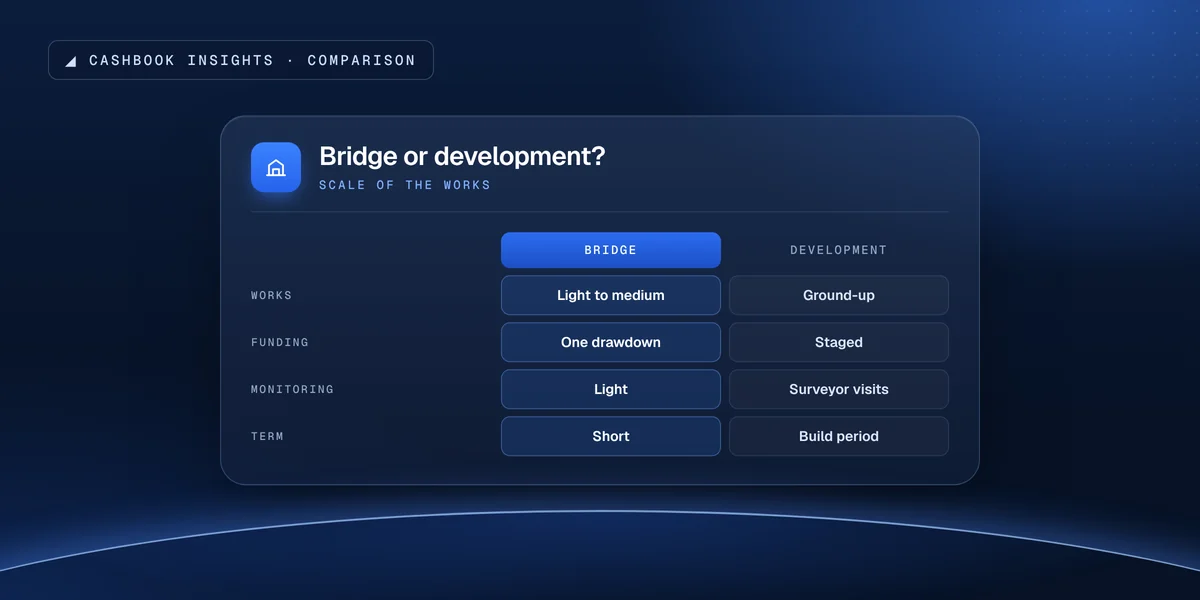
The scale and control of works determine whether a bridge is still the right product.
Light works
A bridge may suit limited refurbishment with a clear budget and exit.
Heavy development
Development finance usually uses monitored stage drawdowns and a detailed build appraisal.
Risk
Planning, construction, cost overrun and sales risk become more significant as the project intensifies.
Examples are educational only. Eligibility, pricing, security and final terms always depend on a formal assessment of your business, your documents and the facility proposed.
Next step
Ready to check the numbers on your case?
A director reviews every application and gives a first view within one working day.