

A home for the borrower
A bridge secured on property the borrower or a close family member lives in, or will live in, is generally a regulated mortgage contract.
In the UK, a bridging loan is generally regulated (as a regulated mortgage contract) when it is secured on a property that the borrower, or a close family member, lives in or intends to live in as a home. Loans secured on investment or business property, taken for business purposes, are generally unregulated.
Bridging structure check
A £325,000 loan against a £500,000 property
Within a 70% illustrative LTV reference point.
A £325,000 loan against a £500,000 property is 65% loan-to-value; equity remaining £175,000.
Security risk: Your property may be repossessed if you do not keep up repayments on a loan secured against it.
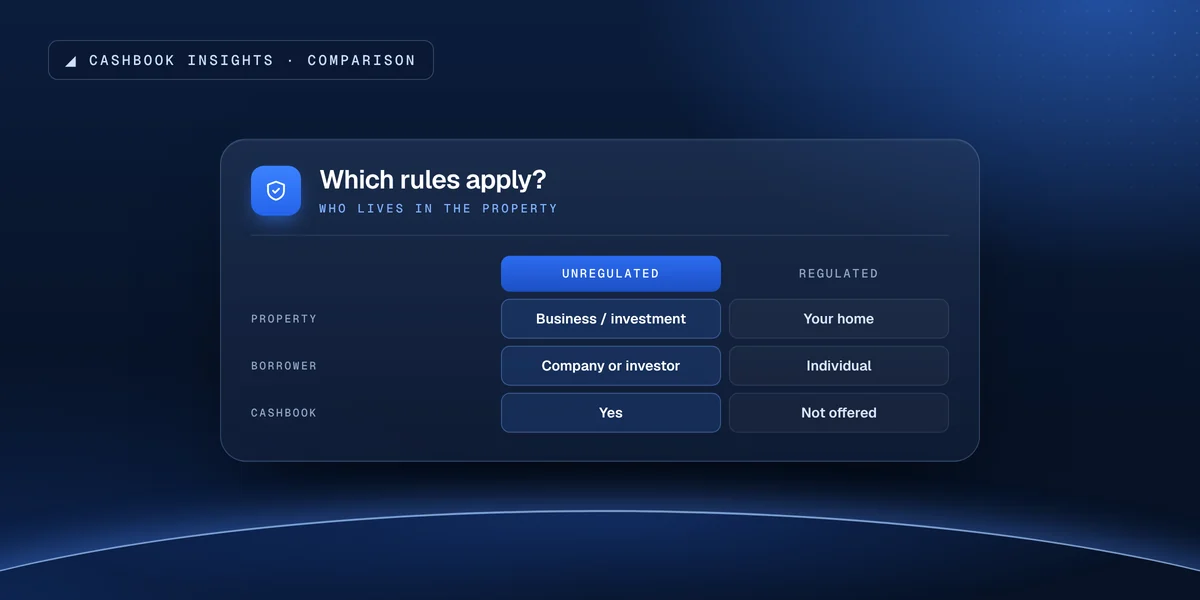
It turns on how the security property is used, not on the size of the loan.Cashbook Finance provides business bridging finance secured on business or investment property.
A bridge secured on property the borrower or a close family member lives in, or will live in, is generally a regulated mortgage contract.
Loans on buy-to-let, refurbishment or commercial property for business purposes are generally unregulated.
Business bridging finance secured on business or investment property.
Regulated or not, a bridge is short-term borrowing secured on property, and the exit - a sale or a refinance - must be credible from the start.
Regulated bridging carries FCA mortgage conduct rules, including affordability and advice requirements. Take advice on your own circumstances, particularly where a property is partly occupied or held through a company.
Which suits you
| Your situation | Usually the better fit | Why |
|---|---|---|
| Buy-to-let, held as an investment | Unregulated business bridge | No one related lives there |
| Commercial or mixed-use property for business | Unregulated business bridge | Business purpose and use |
| Your own home, or a relative’s | Regulated bridge | FCA mortgage rules apply (not offered by us) |
| Part-occupied by family | Take advice before applying | Occupation can make it regulated |
Worked example
A landlord borrows £227,500 against a £350,000 buy-to-let flat that nobody in the family lives in, repaid by a sale in month 9.
Because the property is an investment, not a home, the loan is a business bridge; the costs and the exit still need the same scrutiny.
| Property value | £350,000 |
|---|---|
| Gross loan (65% loan-to-value) | £227,500 |
| Arrangement fee, 1%, from the loan | £2,275 |
| Interest at 1% a month, rolled up, for 9 months | £20,475 |
| Repaid at exit (loan plus interest) | £247,975 |
| Cost before valuation and legal fees | £22,750 |
| If the exit is 3 months late | +£6,825 in interest |
Illustrative: interest at 1% a month, rolled up, and an arrangement fee of 1% of the loan. Valuation and legal costs are extra and quoted per case. Bridging finance is secured against property, which may be repossessed if repayments are not maintained.
Getting the classification right first avoids applying to the wrong type of lender.
Will anyone related to the borrower live in the property?
Is the borrowing for business or investment purposes?
How and when will the loan be repaid?
No. We provide business bridging on investment and commercial property.
Generally, security on a property the borrower or a close family member lives in or intends to live in, as set out in the regulated mortgage contract rules.
Often, but occupation still matters. Take advice if a family member will live in the property.
They carry fewer conduct rules, so read the terms carefully and take independent advice.
Official guidance and legislation on the rules this page refers to. They explain the rules in general; take advice on your own position.
Bridging delays usually come from unclear security, weak exit evidence or legal details that should have been surfaced before the deadline became urgent.
Next step
Tell us how the property is held and used, and we will tell you whether it falls within the business bridging finance we provide.