

Evidence the route to sale
Use realistic pricing, comparable evidence, a credible marketing period and enough time for legal completion rather than relying on an immediate buyer.
The exit is the repayment plan, not a sentence added to the application. It needs a realistic route, evidence, timing margin and a fallback if the first plan slips.
Bridging structure check
A £325,000 loan against a £500,000 property
Within a 70% illustrative LTV reference point.
A £325,000 loan against a £500,000 property is 65% loan-to-value; equity remaining £175,000.
Security risk: Your property may be repossessed if you do not keep up repayments on a loan secured against it.
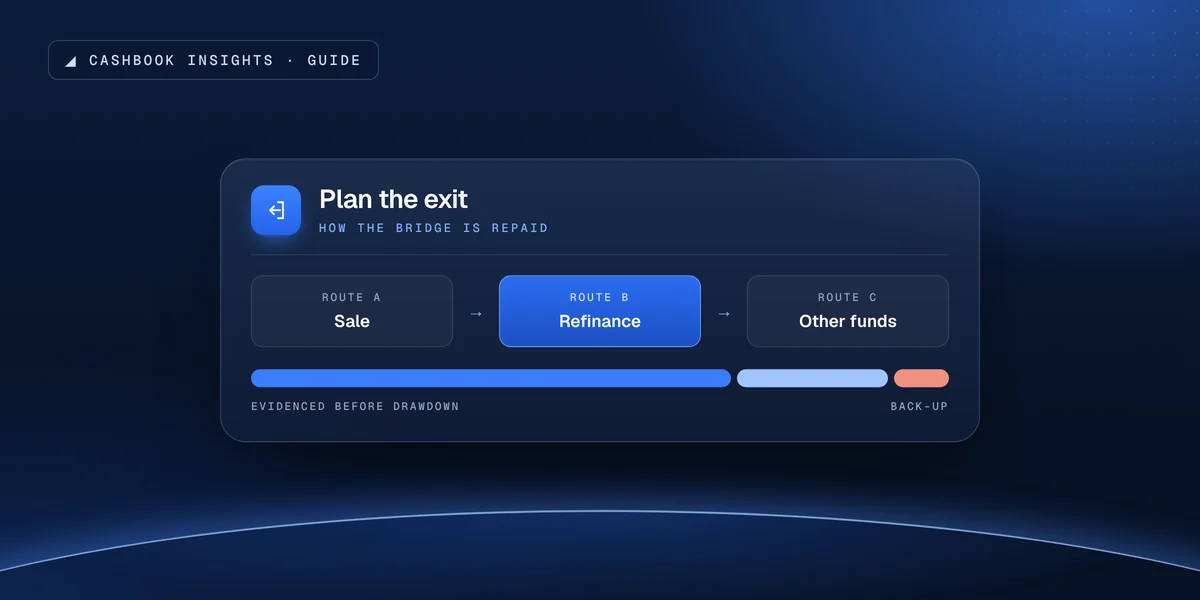
Cashbook Finance assesses a bridging exit as the repayment mechanism for the loan, not as a box-ticking statement. A sale exit should be supported by a realistic value, marketability and timeframe; a refinance exit should be credible against the expected property value, borrower profile and likely long-term lender requirements. The exit must still work if timing or assumptions move against the borrower.
This reflects recurring factors in Cashbook Finance underwriting and case reviews. It is general information, not an approval promise or a substitute for assessment of a specific application.
Urgency does not replace evidence. The lender needs to see how the facility returns to zero within the agreed term.
Use realistic pricing, comparable evidence, a credible marketing period and enough time for legal completion rather than relying on an immediate buyer.
Show the expected lender, affordability or rental coverage, property condition and any work needed before a longer-term refinance becomes available.
A credible backup does not rescue a weak primary exit, but it shows how the borrower will respond if a sale, works programme or refinance takes longer.
A sale exit can be weakened by optimistic pricing, a short marketing window, title issues or works that are not complete. A refinance exit can fail when the expected long-term lender has not assessed affordability, tenancy, condition or planning status.
The useful question is not whether an exit sounds plausible. It is what evidence supports it today, what has to happen next, how long each step can take and what the borrower will do if one step is delayed.
Worked example
A £260,000 bridge against a £400,000 property, with the sale expected in month 8 of a 12-month term.
Three months late is still inside the term here; plan the exit so a delay costs interest, not a default.
| Property value | £400,000 |
|---|---|
| Gross loan (65% loan-to-value) | £260,000 |
| Arrangement fee, 1%, from the loan | £2,600 |
| Interest at 1% a month, rolled up, for 8 months | £20,800 |
| Repaid at exit (loan plus interest) | £280,800 |
| Cost before valuation and legal fees | £23,400 |
| If the exit is 3 months late | +£7,800 in interest |
Illustrative: interest at 1% a month, rolled up, and an arrangement fee of 1% of the loan. Valuation and legal costs are extra and quoted per case. Bridging finance is secured against property, which may be repossessed if repayments are not maintained.
Treat the exit as a dated evidence trail, not a one-word label.
Pricing, comparables, condition, marketing period and legal completion need realistic timing.
Target lender, affordability, rental coverage, property condition and required works need evidence.
A backup route helps, but it does not make a weak primary exit credible.
Bridging delays usually come from unclear security, weak exit evidence or legal details that should have been surfaced before the deadline became urgent.
Next step
Set out the primary exit, its evidence, the target date and a realistic fallback before terms are agreed.