

Get an initial view first
Confirm the lender is comfortable with the property type, expected value and loan size before auction day.
At a traditional UK property auction, the fall of the hammer means exchange of contracts, a deposit is paid on the day, and completion usually follows within about 28 days. That is often too fast for a mortgage, so buyers use bridging finance.
Bridging structure check
A £325,000 loan against a £500,000 property
Within a 70% illustrative LTV reference point.
A £325,000 loan against a £500,000 property is 65% loan-to-value; equity remaining £175,000.
Security risk: Your property may be repossessed if you do not keep up repayments on a loan secured against it.
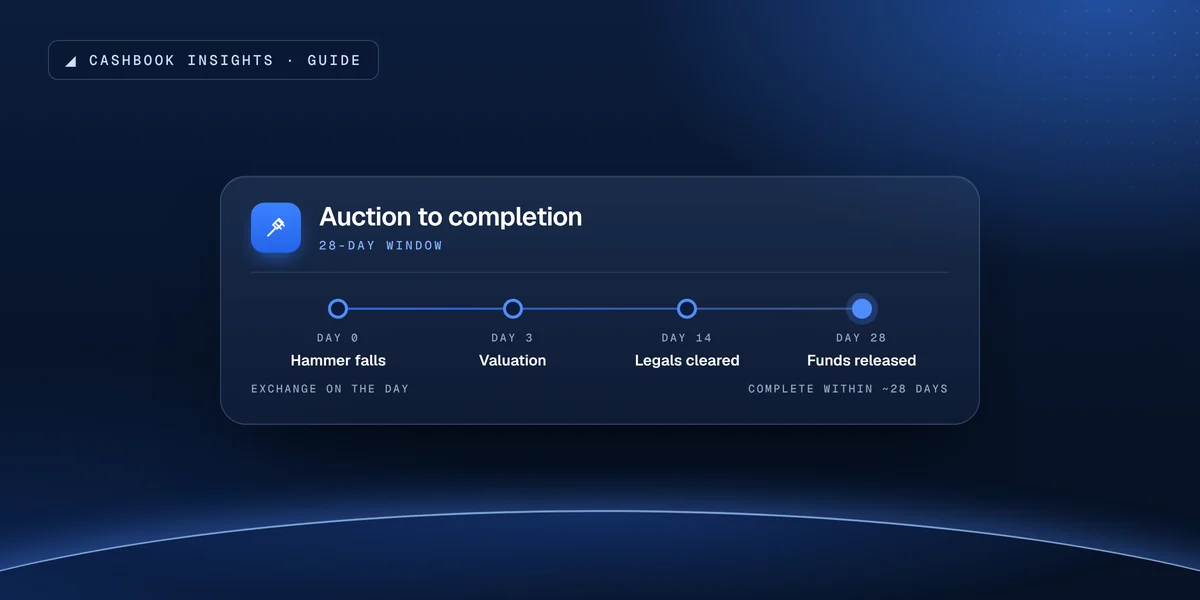
The hammer exchanges contracts. Everything that matters to the lender has to be clear before that moment.The key is to prepare before you bid, because the deadline does not move.
Confirm the lender is comfortable with the property type, expected value and loan size before auction day.
Title, leases, searches, special conditions and extra fees can change the deal, or the lender’s appetite.
A sale or refinance needs to work at realistic values and timings, not just in the best case.
At a traditional auction, completion commonly follows exchange within about 28 days. The valuation, legal due diligence and the loan all have to complete inside that window.
A valuation below the hammer price reduces the loan, and late title or lease problems can stall completion. Missing the date can cost the deposit and more.
Which suits you
| Your situation | Usually the better fit | Why |
|---|---|---|
| You have a buy-to-let or sale exit within 12 months | Auction bridge | Fast enough for 28 days, repaid by the exit |
| The legal pack shows title or lease problems | Do not bid yet | Problems found late can stop completion |
| You can complete in cash and refinance later | Cash, then refinance | No bridging interest at all |
| The lot needs major structural work | Refurbishment bridge or development finance | Works change the value and the risk |
Worked example
An investor buys a flat at auction for £250,000, pays a 10% deposit (£25,000) on the day and must complete within 28 days. The valuation confirms £250,000 and the bridge is repaid by a buy-to-let refinance in month 6.
The investor needs £50,000 more of their own money at completion, plus stamp duty and costs; the bridge covers the rest.
| Property value | £250,000 |
|---|---|
| Gross loan (70% loan-to-value) | £175,000 |
| Arrangement fee, 1%, from the loan | £1,750 |
| Interest at 1% a month, rolled up, for 6 months | £10,500 |
| Repaid at exit (loan plus interest) | £185,500 |
| Cost before valuation and legal fees | £12,250 |
| If the exit is 3 months late | +£5,250 in interest |
Illustrative: interest at 1% a month, rolled up, and an arrangement fee of 1% of the loan. Valuation and legal costs are extra and quoted per case. Bridging finance is secured against property, which may be repossessed if repayments are not maintained.
If any of these is uncertain, the deadline turns a risk into a cost.
A lendable property type, condition and tenure.
A realistic value against the likely hammer price.
A credible sale or refinance route and timing.
You can get an initial view on the property, the loan size and the exit before you bid. The formal offer follows the valuation and legal work, so start as early as the catalogue allows.
The loan is sized on the valuation, so you fund the difference. Keep a cash buffer for that, because the completion date does not move.
At traditional auctions completion usually follows within about 28 days, but the special conditions in the legal pack set the actual date.
We provide business bridging on investment and commercial property. A home you or your family will live in falls under regulated lending, which we do not offer.
Official guidance and legislation on the rules this page refers to. They explain the rules in general; take advice on your own position.
Bridging delays usually come from unclear security, weak exit evidence or legal details that should have been surfaced before the deadline became urgent.
Next step
Share the lot, the legal pack and your exit plan, and we will give you a straight view on fit before you bid.